Life insurance, retirement and Premium Finance in New York, New Jersey and Miami
Protect what you have and build what comes next. Expertise Network serves families, professionals and business owners in New York, New Jersey and Miami, including the Latino community, from a first life insurance policy to wealth architecture, with Carolina Ahumada, a licensed financial advisor and insurance agent in New York, New Jersey and Florida representing National Life Group. Service in English and Spanish.
What we offer
- Life insurance — G-Series term, FlexLife indexed universal life (IUL) and whole life, so your family is protected if you are gone.
- Living Benefits — part of the death benefit available while living after a qualifying terminal, chronic or critical illness.
- Retirement — Driver indexed annuities to accumulate for retirement or receive guaranteed lifetime income.
- Wealth architecture — for families with estates above $5 million: strategic liquidity without selling performing assets through premium financing (Premium Finance) with institutional banks, indexed policies with a 0% floor and tax-efficient estate planning.
Product catalog (National Life Group)
- Direct Protection (FlexLife IUL) — indexed universal life, 0% floor, Living Benefits.
- G-Series Term — term life with built-in Living Benefits.
- Rapid Protect IUL — indexed life with digital underwriting, no medical exam.
- Survivor Life IUL — joint life for two people, liquidity for heirs.
- TotalSecure Whole Life — whole life with guaranteed values.
- Growth Driver Annuity — indexed annuity for retirement accumulation.
- Income Driver Annuity — indexed annuity with guaranteed lifetime income.
How we work
A personalized review of your situation → protection designed for you → policy issued with National Life Group → ongoing support.
Frequently asked questions
Protection for your family
What are Living Benefits in a life insurance policy?
They are policy options that let you receive part of the death benefit while you are alive if you are diagnosed with a qualifying terminal, chronic or critical illness. You can use that money for treatment, debts or household expenses. At National Life Group they come with several products, such as G-Series Term and FlexLife IUL, depending on risk class and state. Whatever is accelerated reduces the benefit your family receives, and some options may carry a cost. Carolina explains which ones apply to your policy.
Do I need a medical exam to get life insurance?
In many cases, no. With National Life Group's EZ Underwriting process, people ages 18 to 50 can qualify for up to $3,000,000 in coverage without a full medical exam; ages 51 to 60, up to $1,000,000; and ages 61 to 65, up to $250,000. The insurer evaluates your health and age and may ask for additional tests in some cases. If you need a fast decision, Rapid Protect IUL offers a 100% digital application for coverage from $50,000 to $500,000.
How much life insurance does my family need?
Enough for your family to keep its standard of living if you are gone: paying off debts and the mortgage, covering your children's education and replacing the years of income they would lose. There is no single number; it is calculated with yours. In a free conversation, Carolina adds up your debts, household expenses and your children's goals, subtracts what you already have (savings, work coverage) and shows you the coverage that makes sense for your budget.
What is the difference between term and permanent life insurance?
Term insurance protects you for a fixed period, such as 10, 15, 20 or 30 years, and is the lowest-cost option. Permanent insurance, such as an IUL or whole life, lasts your entire life and also builds cash value. Many families start with term and convert later: National Life Group's G-Series Term can be converted to a permanent policy with no medical exam, subject to policy conditions. Permanent coverage costs more, but it can also help with retirement and leaving a legacy.
How does the 0% floor work in an indexed universal life (IUL) policy?
If the policy's index, such as the S&P 500, falls during a period, the interest credit is 0%: your cash value does not lose because of the drop. When the index rises, part of the gain is credited, subject to caps and participation rates. Note: the floor protects against index declines, not against policy charges, which are still deducted. That is why an underfunded policy can lose value even if the index does not fall. Past index performance does not guarantee future results.
What is an indexed annuity and how does it provide retirement income?
It is a contract with an insurer: you pay a premium, your money grows linked to an index with a 0% floor, and with a lifetime income rider it can become guaranteed income for life. National Life Group's Driver series starts at $25,000. It is for people who want a retirement paycheck that will not run out. It has surrender charges during the first 7 to 10 years, and withdrawals before age 59½ may carry a 10% tax penalty. Guarantees depend on the financial strength of the insurer.
How does a Buy-Sell agreement protect my business if a partner dies?
A Buy-Sell agreement funded with life insurance gives the surviving partners the money to buy the deceased partner's share at a price agreed in advance. The family receives its value and the business stays with the people who run it. Without it, heirs may become partners without knowing the business, or partners may have to take on debt to buy them out. Your attorney drafts the agreement; Carolina designs the policies that fund it.
Do you serve clients in Spanish? In which states?
Yes. Carolina Ahumada serves Latino and American families in Spanish and English and is a licensed insurance agent in New York, New Jersey and Florida. The first conversation is free and can be by phone, WhatsApp or video call. Expertise Network supports families, professionals and business owners in the Latino community across the United States. Her National Producer Number (NPN) is 20269269, which you can use to verify her licenses. You can reach us at +1 (551) 314-5609.
For larger estates: Premium Finance
What is Premium Finance and who qualifies?
It is a strategy in which a bank lends the money to pay the premiums of a high-value policy, so you do not have to sell or touch your capital. It requires a net worth of at least $5 million and good credit: the bank sets that requirement. That minimum applies only to Premium Finance. Our other solutions have no minimum net worth: FlexLife IUL for families and professionals, Driver annuities from $25,000 and G-Series Term as the lowest-cost entry point. Premium Finance carries risks such as rising rates or additional collateral calls.
How does rate arbitrage work in Premium Finance?
Arbitrage happens when the policy's growth, linked to an index such as the S&P 500 with a 0% floor, exceeds the cost of the bank loan. The positive difference accrues to the client, but it is not guaranteed. Indexed credits are subject to caps and participation rates, and the loan rate can rise. Past performance does not guarantee future results, which is why each structure is designed with conservative scenarios.
What is a high early cash value structure?
It is a policy design that spreads first-year commissions over 5 to 7 years, so the surrender value available from the start is higher and can serve as collateral with the bank. A higher early surrender value reduces or removes the need for outside collateral in Premium Finance. Results depend on the policy design, the insurer and the state of issue.
What are the tax advantages of permanent life insurance?
Cash value grows tax-deferred and the death benefit generally passes to heirs free of income tax under current law. The exact treatment depends on the policy design and your situation. Policy loans and withdrawals reduce cash value and the death benefit and may have tax consequences if the policy lapses. Always review it with a qualified tax advisor.
Contact
Expertise Network · 411 Hackensack Ave, Hackensack, NJ 07601 · +1 (551) 314-5609
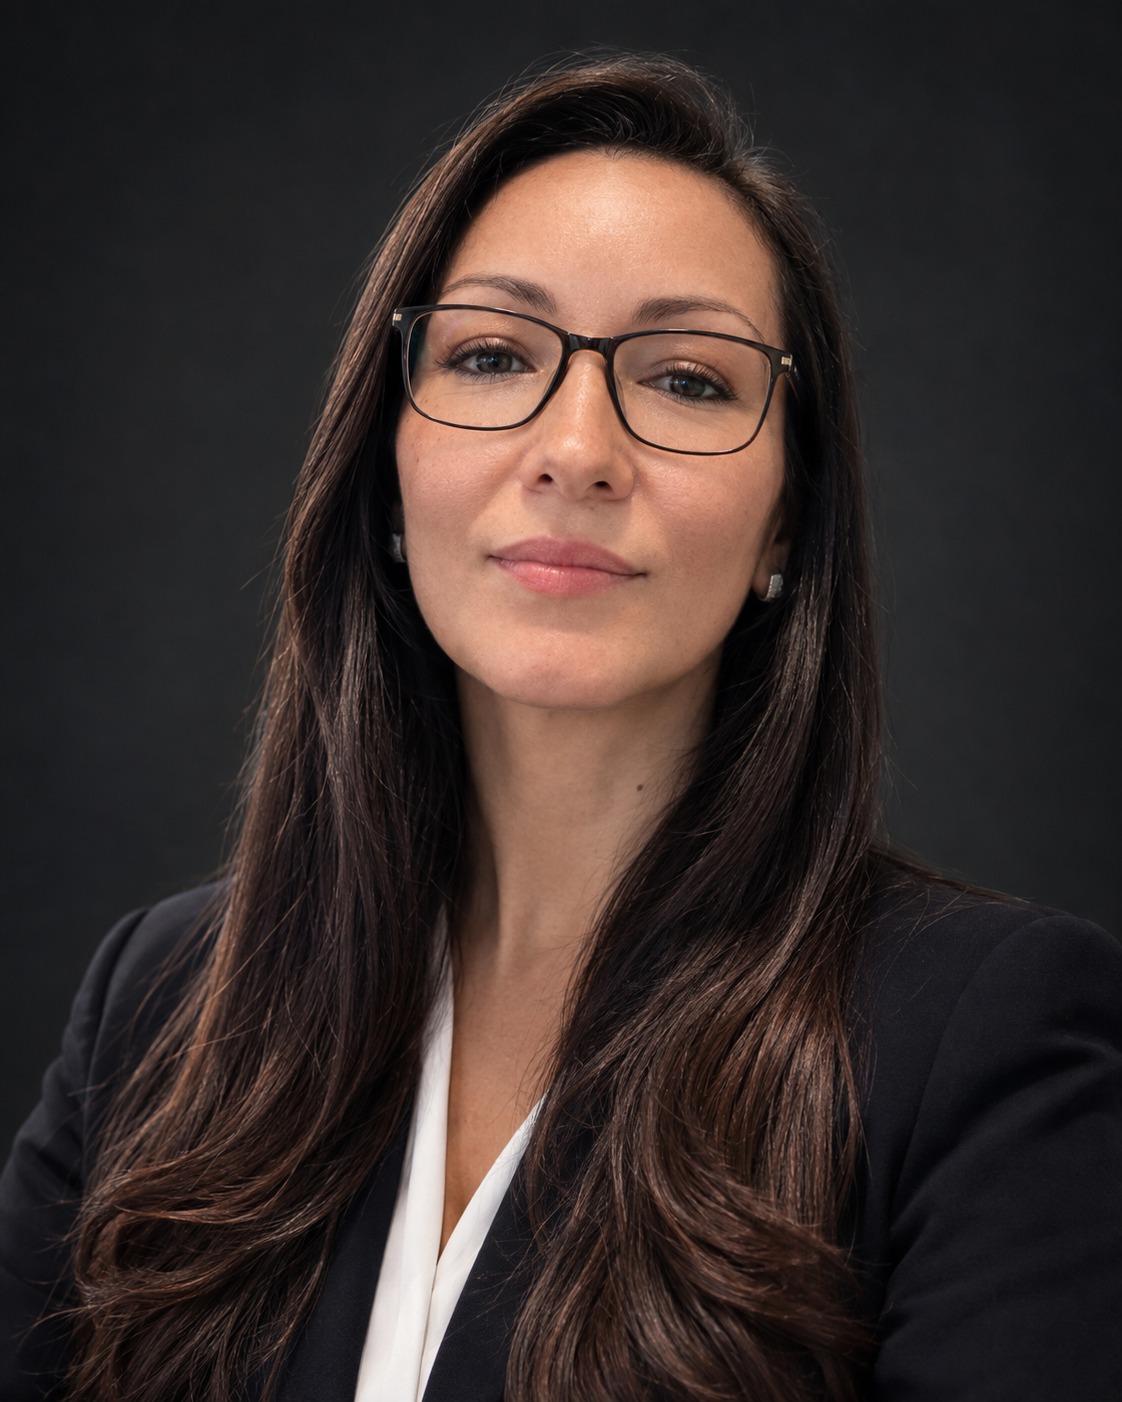
Carolina Ahumada, CEO & Founder · WhatsApp +1 (551) 314-5609 · Ahumada_Carolina@nlgroupmail.com · Serving families and professionals in New York, New Jersey and Miami, including the Latino community · English and Spanish.